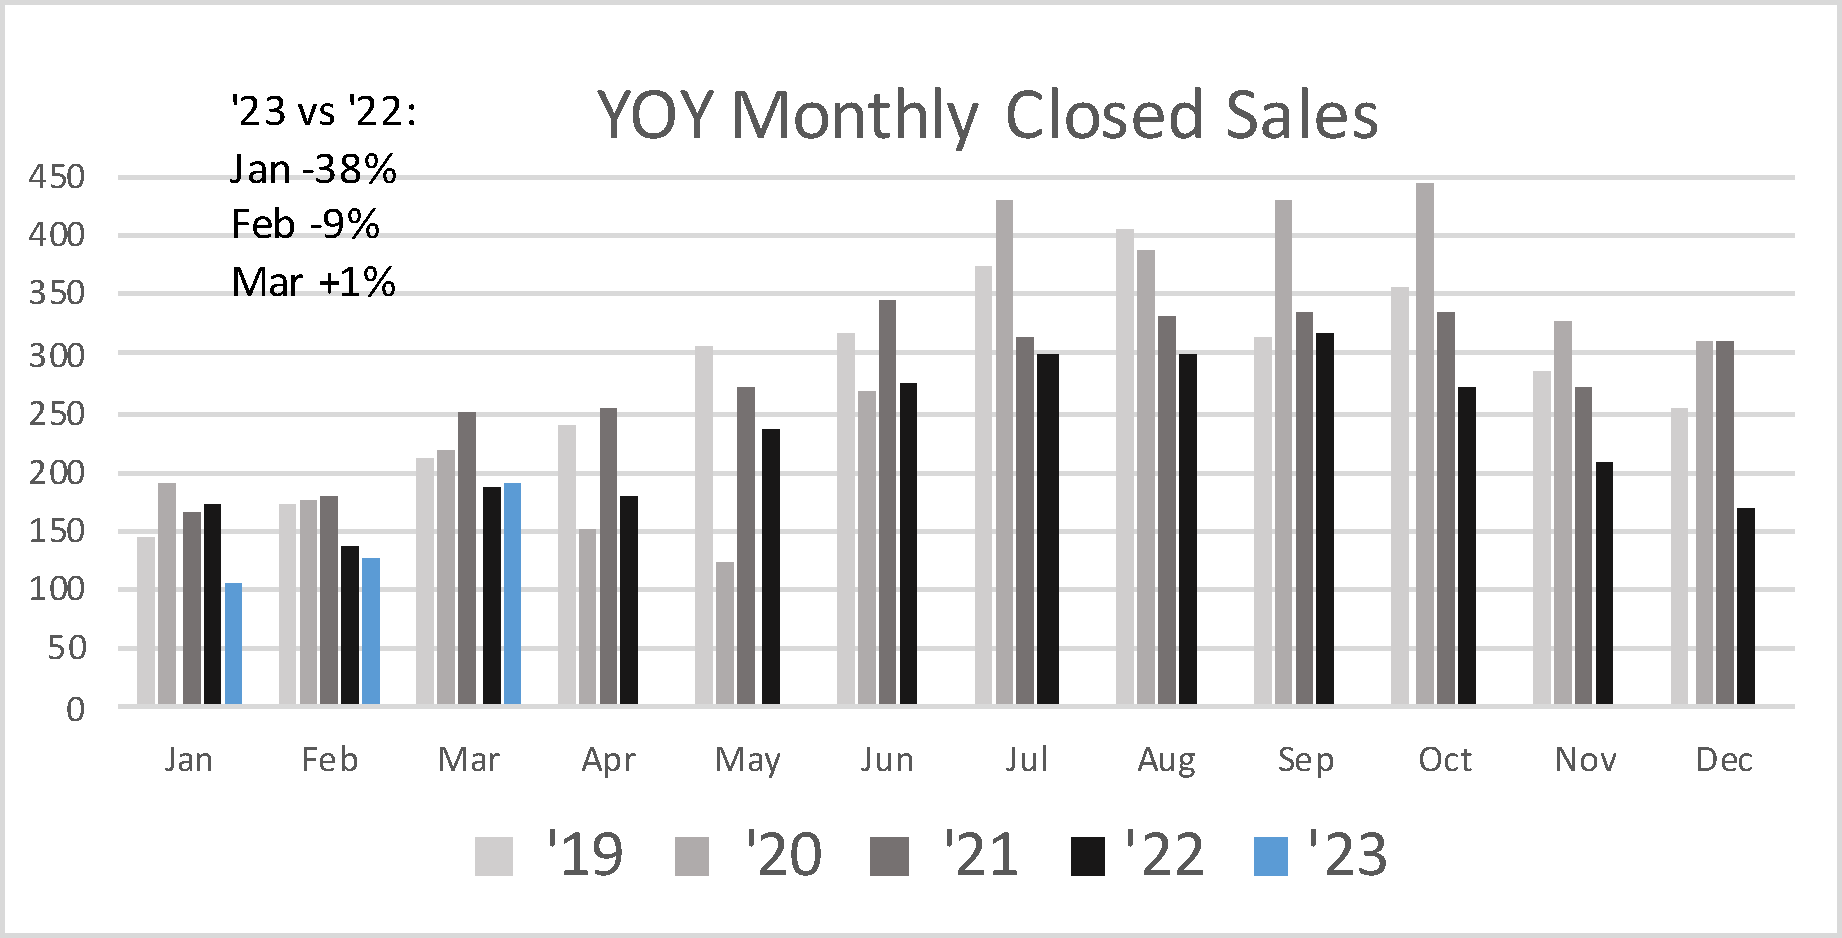
Despite continued strong demand, limited active inventory quantity and quality continues to bottleneck sales. Buyers are waiting and jump when fresh inventory arrives. March closed sales were up 50% compared to the prior month, and a 29% increase in new pendings will continue to lift April and May closed sales.
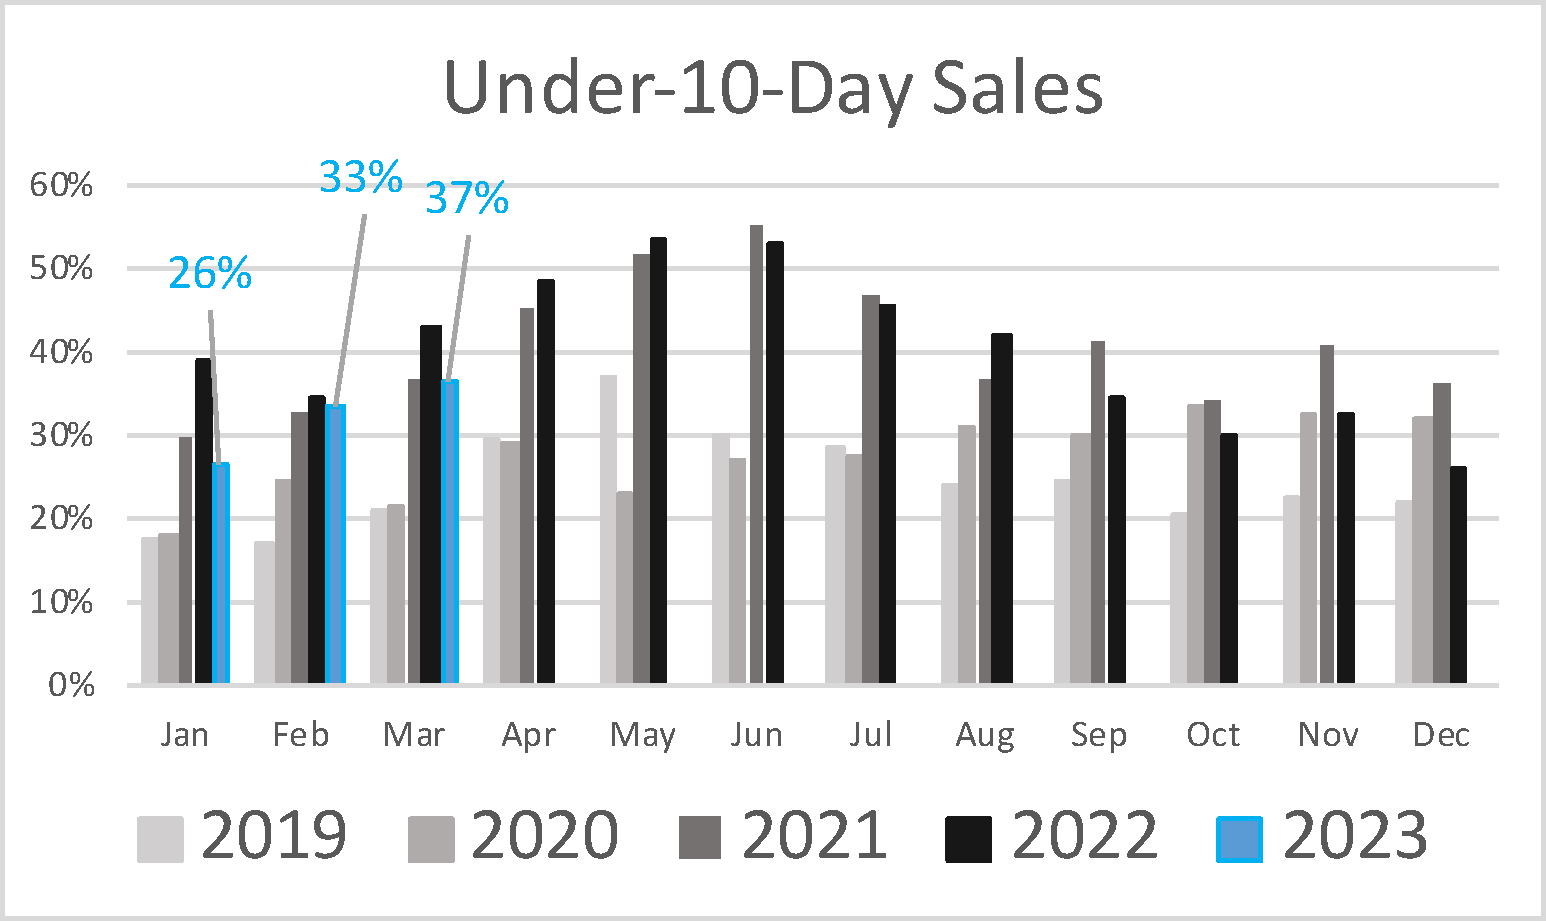
The best listings continue to sell quickly. The 10-day sales chart shows 37% of March new sales were on the market for 10 days or less. While that’s short of last year’s historic 43%, it ties the previous high set in 2021 and is nearly double pre-pandemic figures. Demand remains high despite inventory and affordability challenges.
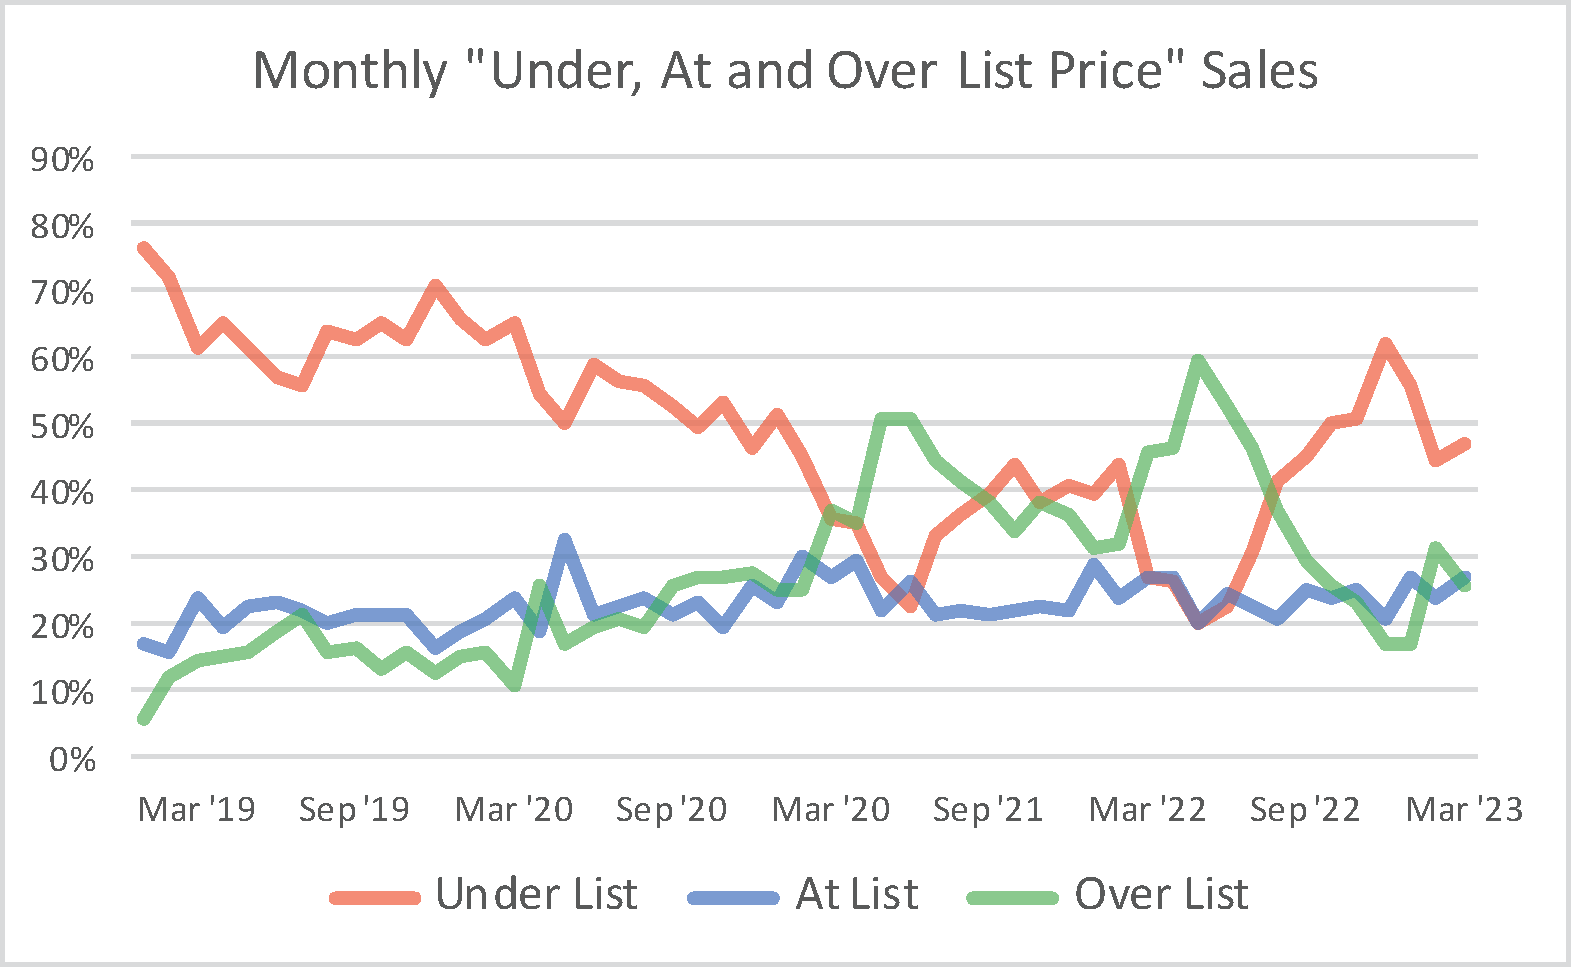
Twenty-six percent of March closed sales were above full asking price, 27% were at asking and 47% were below asking. Like new sales activity, “over” offers jumped in February when interest rates were temporarily lowered, but faded in March as rates returned to where they were. Buyers continue to wait for their “something special”. Expect buyer competition to heat up as fresh new listings hit the spring market or if there’s another dip in rates.