Summary
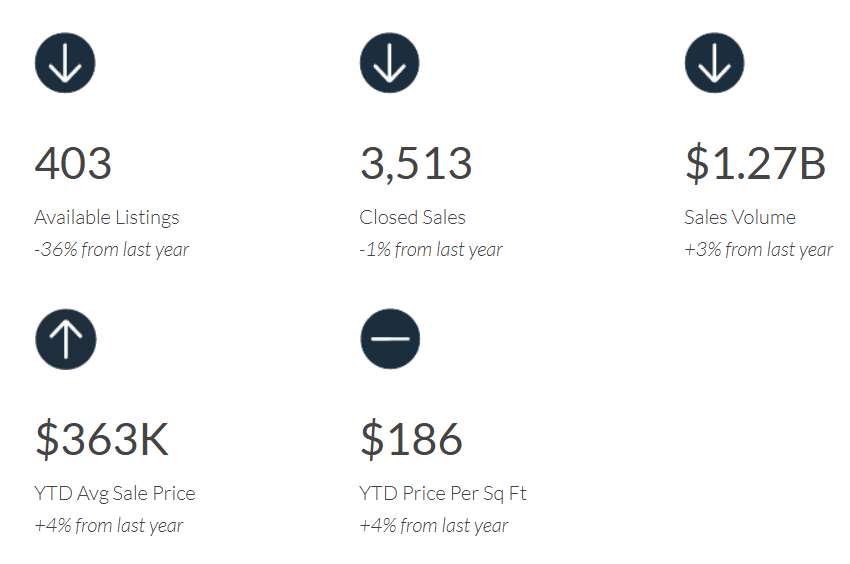
Inventory— Active listings are down 36% from a year ago. In the entry and middle (under-$300k) price ranges, there’s less than 1 month of inventory—down 60%).
Closed Units— Despite the spring “lockdown”, 2020 closed sales were nearly even with the prior year—down 1%. Sales priced below $150k were down 21% as due to a lack of inventory. Over-$150k sales were up about 20%.
Values— The 2020 Average sales price rose 4% over 2019. Most of the increase for the year occurred in the lower price ranges. While upper-end values dropped in the first half of the year, they were up YOY by 4% and 6% in the 3rd and 4th quarters. Expect that momentum to carry over into 2021.
Summary— With less than one month of under-300k supply, inventory continues to limit sales. Inventory isn’t as restricted in the upper price range. Upper-end prices dropped in the early months of COVID but made a second half recovery. Expect a greater proportion of sales to shift towards the upper price ranges. Values will rise at all levels.