Summary
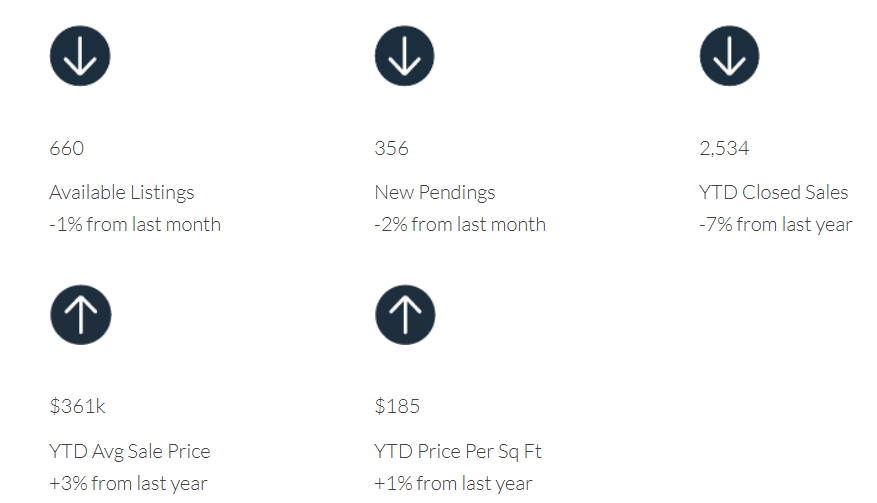
Inventory continues to decline—it’s down 34% year-over-year. Although monthly showing activity has declined each month since June, showings continue to run 15% higher than a year ago. YOY new pendings were up 22% in August/September, but have been trending down since the beginning of October. Closed sales peaked with record highs in July. Monthly sales have been declining since, but still running 20 to 30% higher than last year. Values, which dipped during the Covid “shutdown,” have been rising. YTD average sale price and price per square foot are both up slightly, but mostly due to a shift in the product mix—fewer lower and middle-priced sales because of limited low-priced inventory.