Single Family Summary
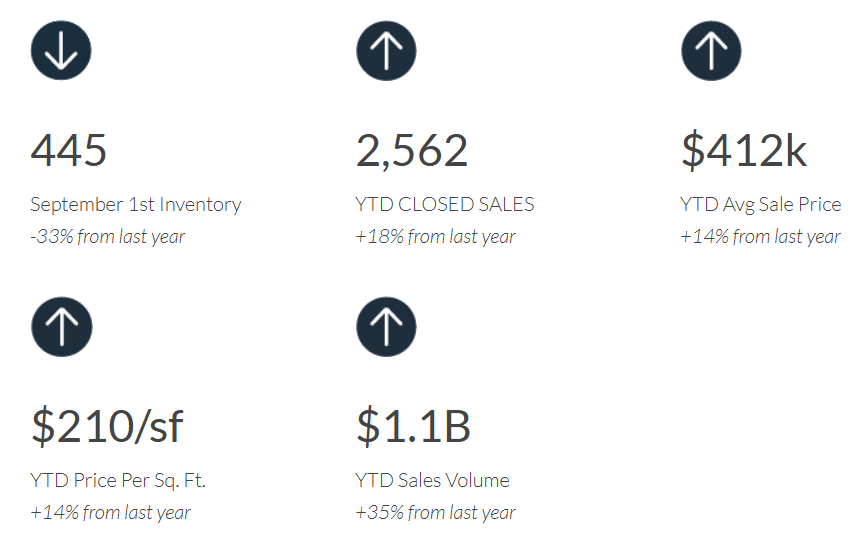
Inventory— Available listings peaked in August at 500, but have been dropping off since. They are down 33% compared to the same time last year.
Closed Units— Monthly closed sales peaked in June and have been declining since. Expect some leveling over the next couple of months before the fourth quarter decline as the market normalizes into traditional seasonal trends. YTD sales are up 18% compared to last year and 6% compared to 2019.
Values— Values rose sharply earlier in the year as buyer competition and bidding drove up prices. They leveled in June and have been adjusting down since. YTD average sale price and $/SF are both up 14%.
Summary— Expect buyer competition and prices to ease as the market moves into the fourth quarter.
Condo Summary
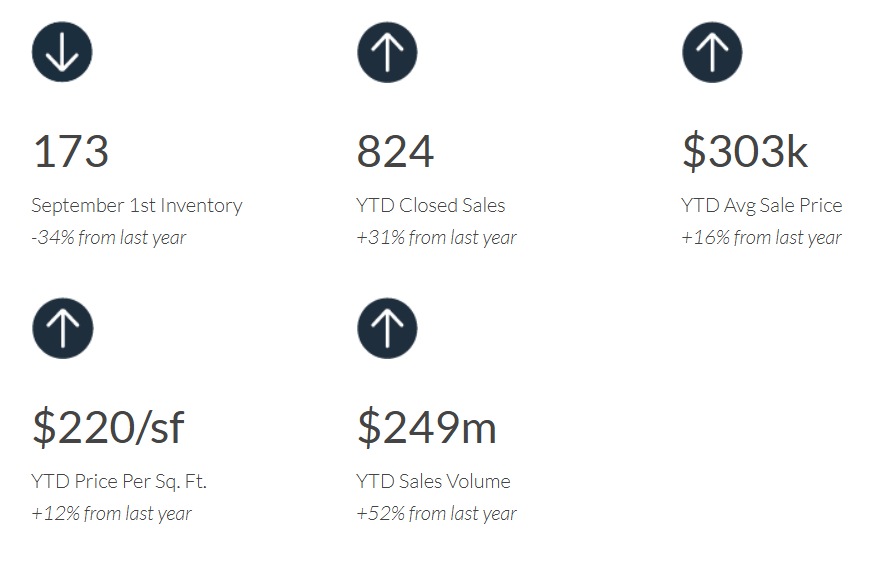
Inventory— Condo inventory grew through spring, peaked in July and has been declining since. It dropped 9% in the past month and 34% since this time last year.
Closed Units— After slowing down in the middle of the pandemic, condo sales have been rebounding. YTD sales are up 31% compared to last year and 19% compared to 2019. Expect the energy of that bounce to ease as we head into the fourth quarter.
Values— Strong demand and buyer competition drove prices up sharply in the spring. Prices have since eased off as many of those who had been looking have now bought. Expect buyer competition and prices to ease as the market returns to more traditional seasonality.
Summary— After an initial COVID chill, condo markets had a strong bounce back through the first half of this year. Expect fourth quarter slowdowns as the market settles.