Despite continued strong demand, limited active inventory quantity and quality continues to bottleneck sales. Buyers are waiting and jump when fresh inventory arrives. March closed sales were up 33% compared to the prior month, and a 35% increase in new pendings will continue to lift April and May closed sales.
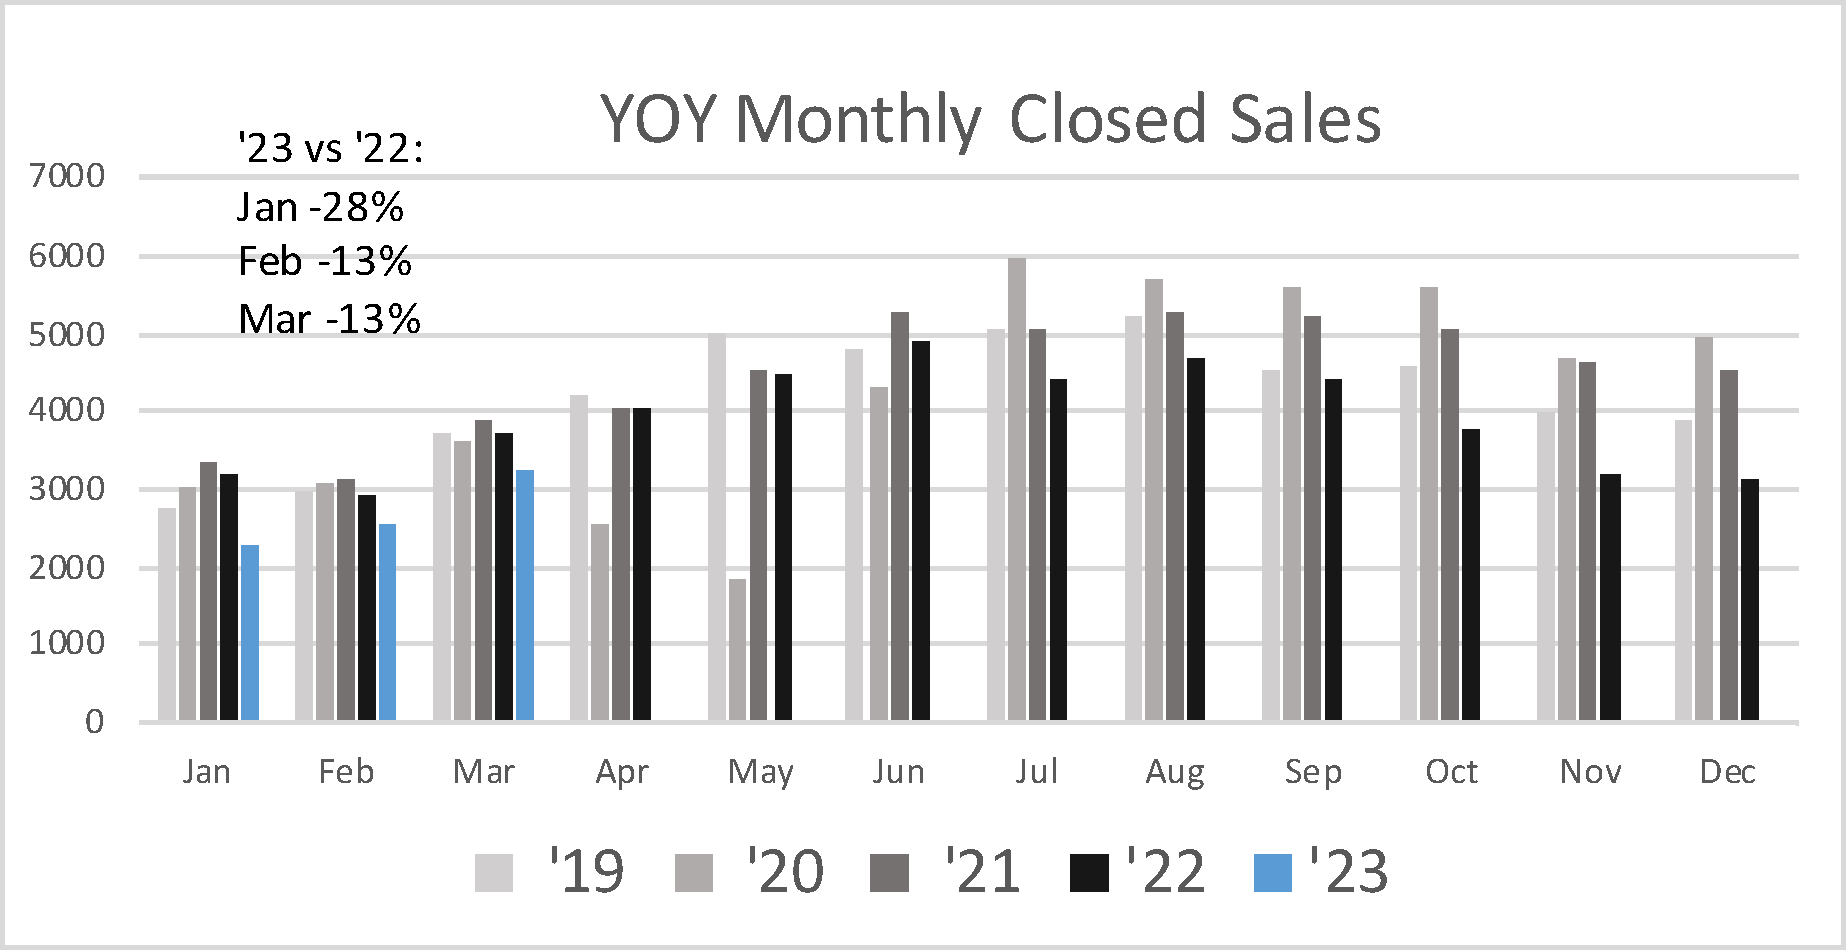
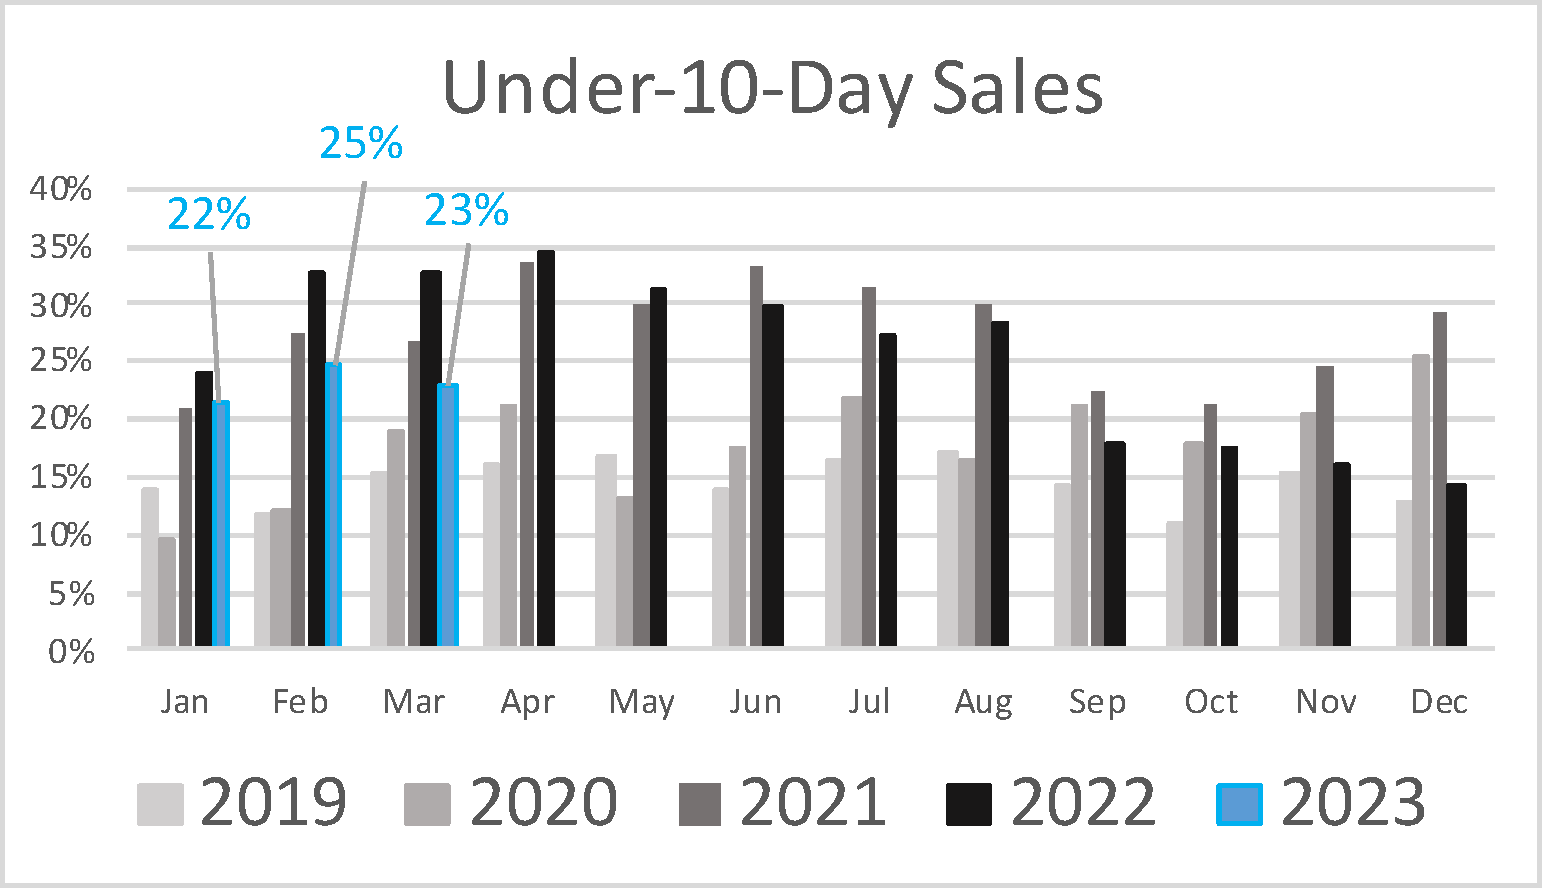
While the market lacks last year’s intensity, the best listings continue to sell quickly. The slight increase in February may have been a reaction to a temporary dip in interest rates. New pendings also ticked up at that time.
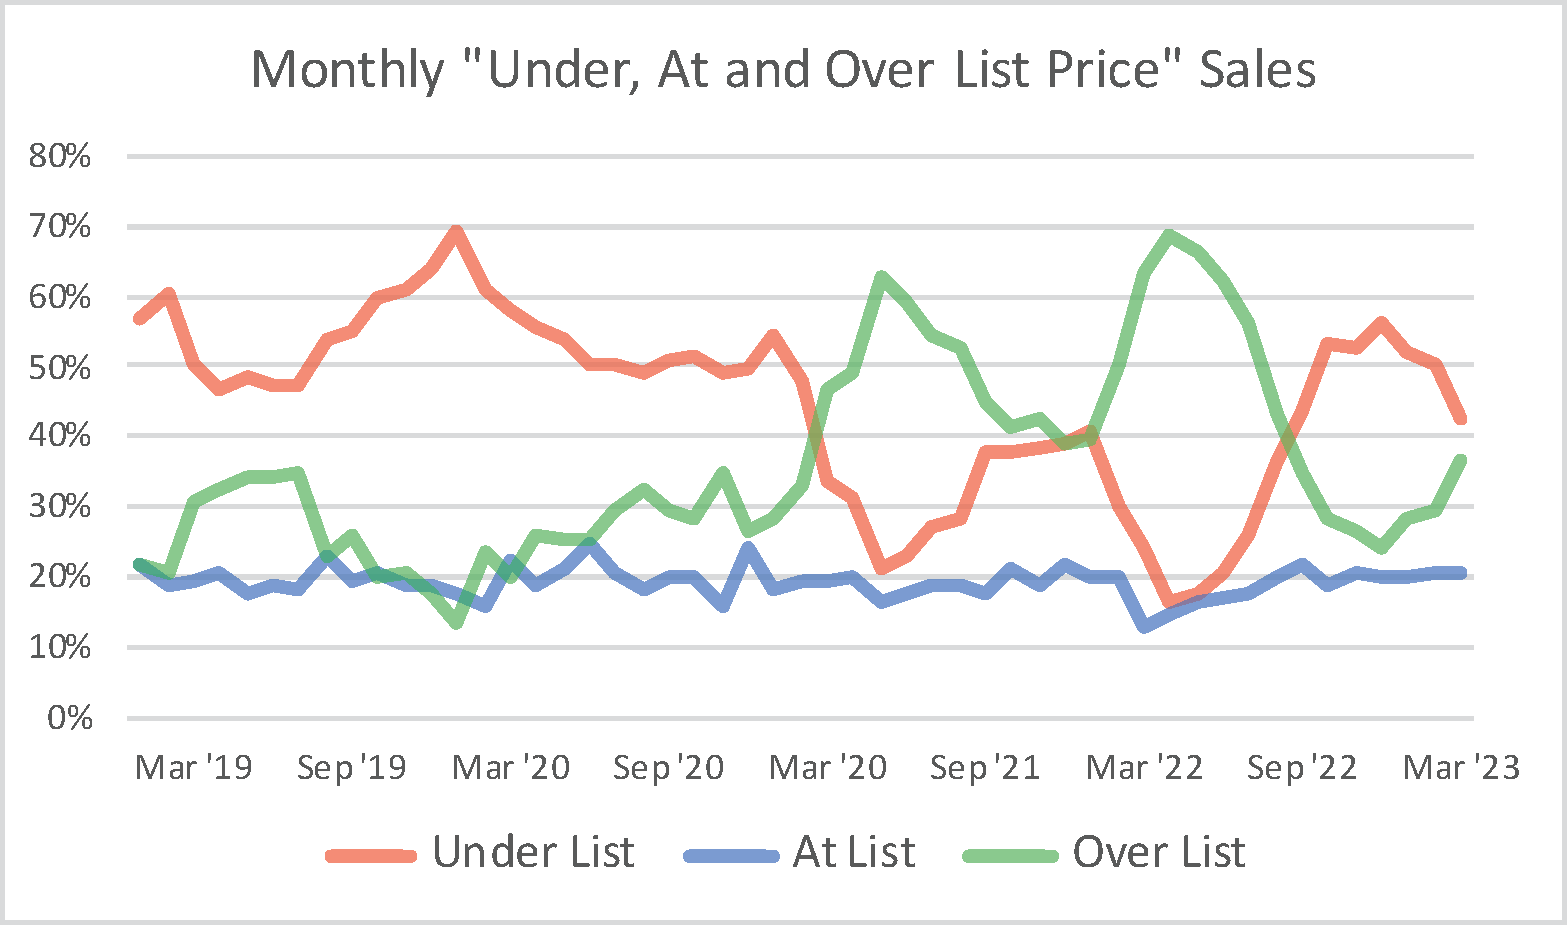
Thirty-seven percent of March closed sales were above full asking price, 21% were at asking and 43% were under. As shown in the “Under, At and Over” chart, the “Over” sales are increasing while the “Under” sales are decreasing. Expect the Over-Asking percentage and market intensity to peak just before summer as it has done the past two years.