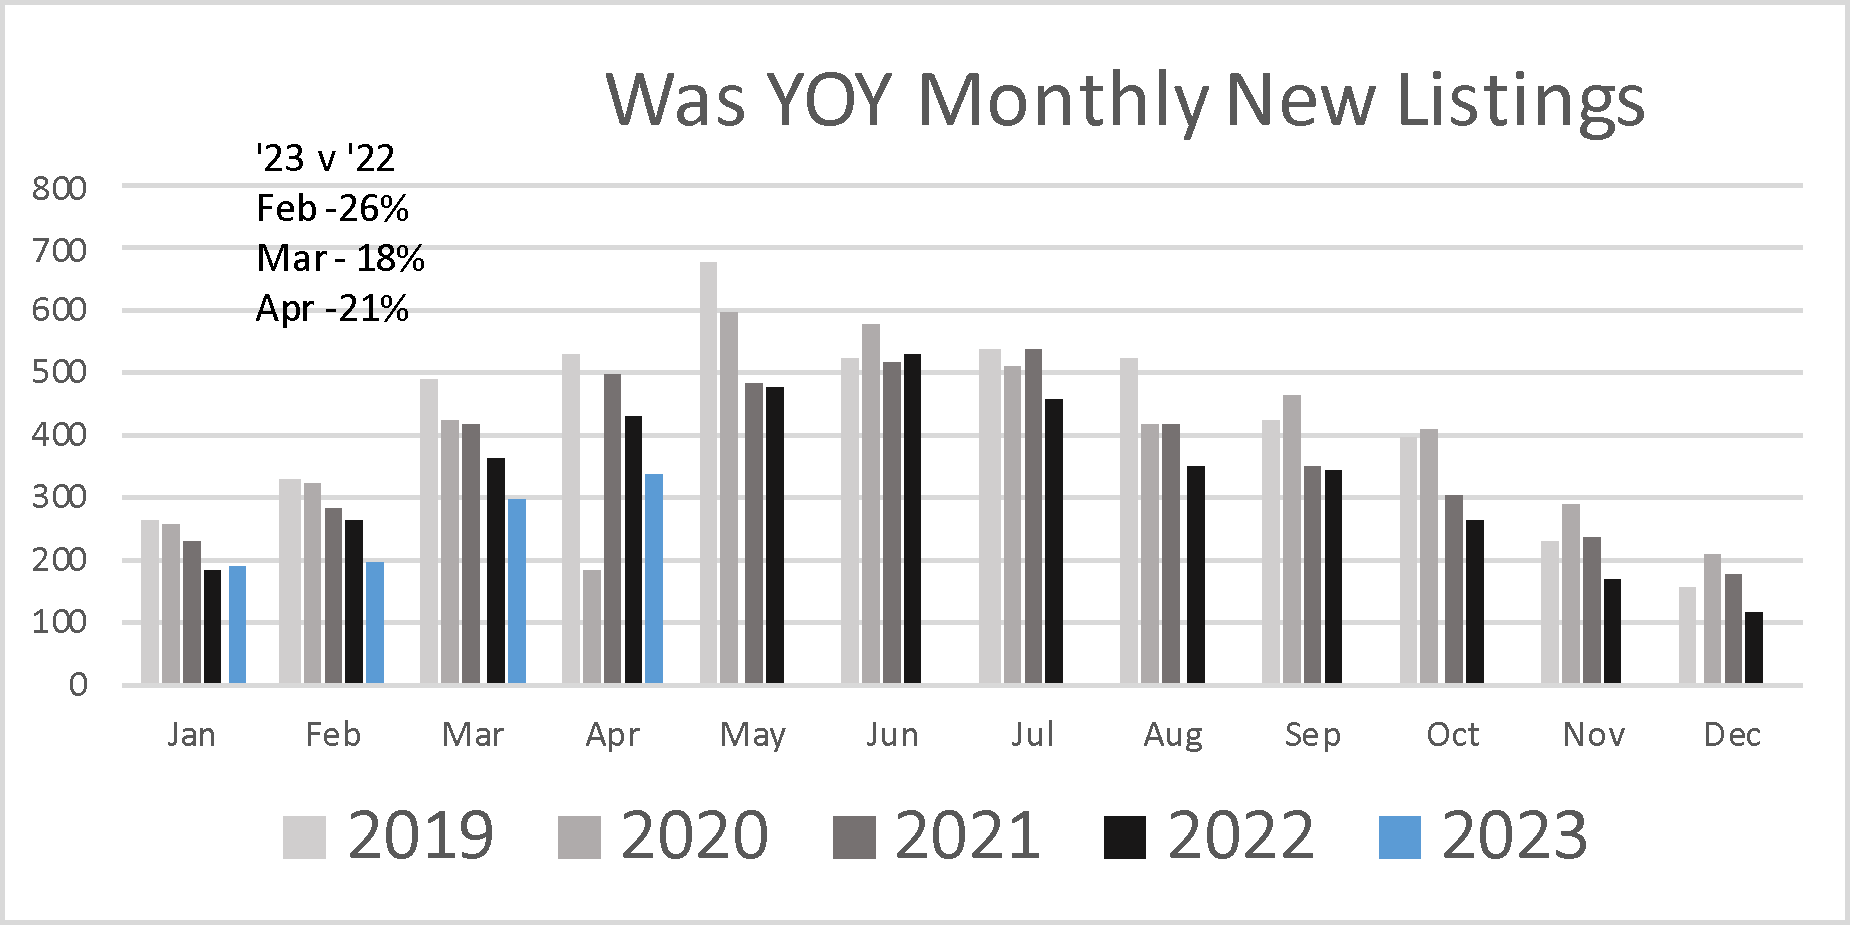
While the arrival of new listings should reach last year’s levels during the latter half of this year, there’s been a noticeable delay though the early months of this year. Buyers continue to face extended waiting periods and intensified competition due to the persistent scarcity of top quality listings.
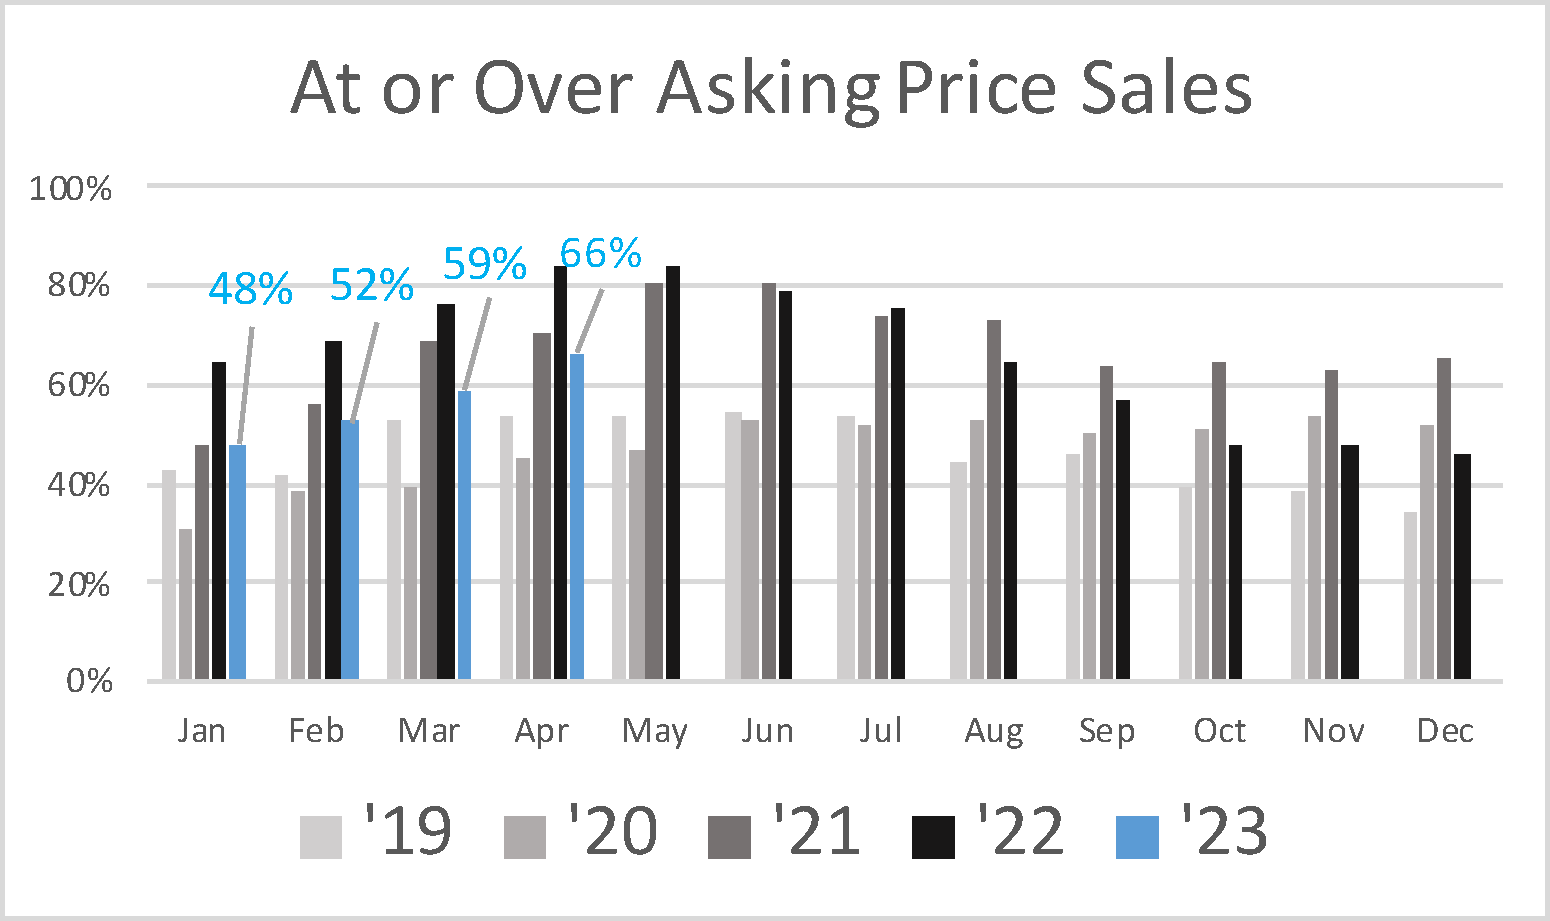
The market frenzy isn’t as heated as last year, but an impressive 66% of last month’s closed sales were either at or above the full list price, a drop from 84% last year. Sellers with well maintained, move-in-ready properties continue to receive over-asking offers. Buyers who are lucky enough to find these unique listings need to be creative in crafting offers that rise above their rivals’.
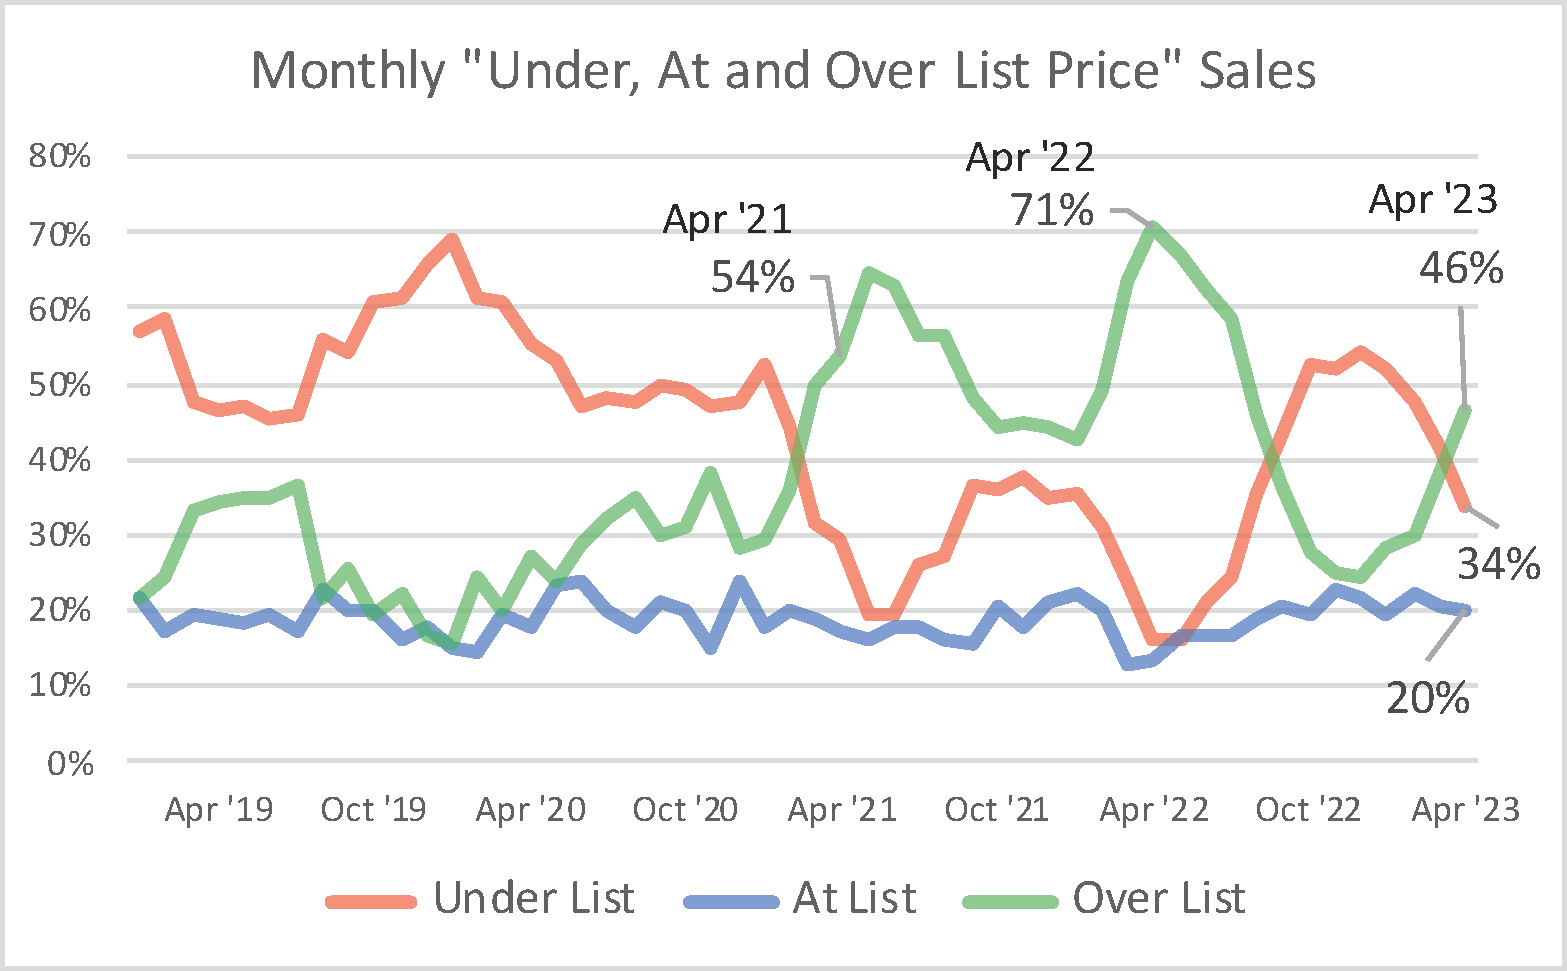
In April, 46% of closed sales exceeded the full asking price, 20% were equal to it and 34% fell short. Compared to 2022 and 2021, our market is operating on a delayed schedule. The 2023 peak for over-asking sales will be a few months away.
Using a Tortoise and the Hare comparison—last year’s market had an extremely rapid start but abruptly dropped off in June and through the balance of the year. This year’s market has had a slower launch, but business is expected to be more consistent and fade slower in the second half of the year.